Country risk over 600 points as US hikes interest rates
 Juan Marcos PollioUpdated 10 hours Ago3 Mins read
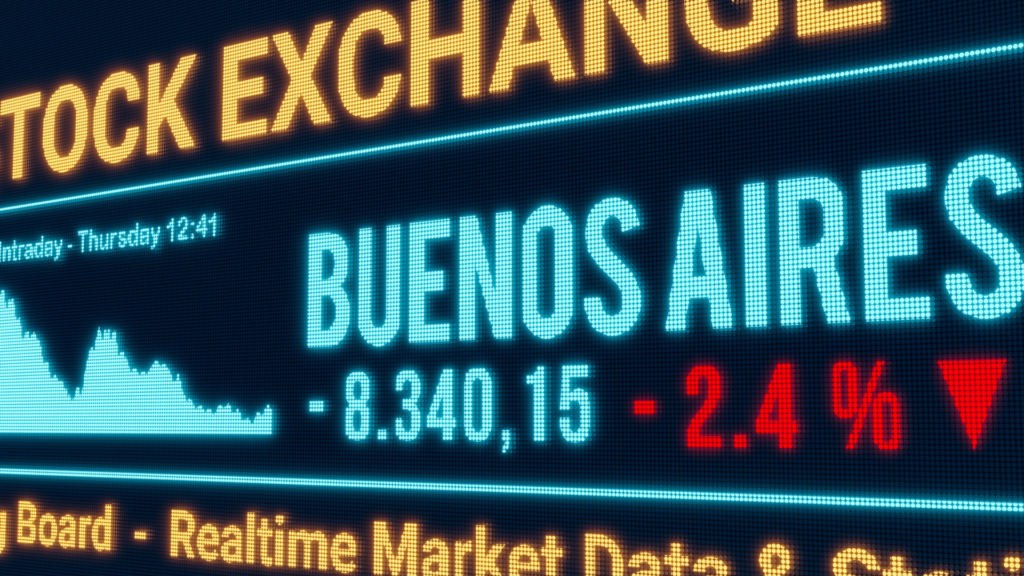

The JPMorgan EMBI+ index for Argentina, known as “country risk,” has been rising in recent weeks due to uncertainty surrounding next year’s elections, recent economic data, and lower reserve purchases by the Central Bank.
Renewed volatility in United States Treasury bonds over the last week — which sent their yields soaring to levels not seen in more than two decades — only exacerbated this problem.
On Friday, Argentine debt bonds issued under New York law fell again, accumulating a drop of up to 4% in just the last five trading sessions.
This caused country risk, which reflects the interest rate Argentina would pay to borrow abroad, to rise to 602 basis points in the week’s final trading session. In mid-July, the index was at 402 points, its lowest level since April 2018.
So far this month, the index has accumulated a 22% increase.
Pablo Repetto, head of research at brokerage firm Aurum Valores, told the Herald that the increase in country risk is the result of both international and local factors.
On the global front, the development is tied to “the rise in risk-free interest rate,” i.e., the rate on U.S. bonds. In the 30-year segment, for example, Treasuries reached a 5.9% yield, the highest since 2004.
With higher U.S. rates, investing in Treasuries becomes more profitable and less risky than putting money into emerging markets such as Argentina.
That not only weighs on the price of Argentine bonds, it also strengthens the dollar on international markets, making Argentine debt — much of it denominated in dollars — harder to service.
Why are US bonds rising? The rise is due to many factors. Repetto noted that inflationary pressures “remain firm in the United States,” fueling predictions that the Federal Reserve will keep raising its benchmark interest rates.
According to the FedWatch tool from consulting firm CME Group, there is more than a 64% chance that they will increase the rate by 25 basis points at the October 28 meeting.
A recent market analysis by Portfolio Personal Inversores (PPI) brokerage firm said that there appears to be no “short-term resolution” to the war in the Middle East, as Iran appears to have “incentives to extend it at least until the U.S. midterm elections in November.”
This raises inflation expectations in the short and medium term.
Another problem is that the conflict with Iran forces the U.S. government to continue financing the war. “This deteriorates fiscal balance, one of the structural factors pushing up the cost of U.S. Treasury financing,” analysts at PPI explained.
Added to that is the fact that the conflict complicates the macroeconomic outlook for other powers. Japan or Europe, to name two, are also recording widespread sell-offs of sovereign debt.
“This makes their local yields more attractive and provides greater incentives for foreign holders of ‘Treasuries’ to repatriate their capital,” the PPI analysts said.
Finally, Repetto highlighted that the constant issuance of debt associated with investments in artificial intelligence creates competition between corporate and government debt. This impacts the global interest rate structure and creates repercussions for the sovereign debt of countries, including Argentina.
Local factors behind the rise in country risk In addition to the international factor, there are also local factors at play causing uncertainty among investors.
“Negative readings in economic activity and poverty indicators raise caution [in market actors], as they reflect the difficulties facing the ‘micro’ economy,” said economist Gustavo Ber.
Poverty in the first half of 2026 rose to 32%, while activity plummeted 2.9% monthly in July.
Ber said that this weakness could be crucial due to its effects on “social mood” as electoral strategies begin to take shape.
For Repetto, the problem is not that the country risk could shoot up to over 600 points, but rather that 400 points is actually “quite low.”
Having country risk in the 600-point range, he added, would not be illogical in a pre-electoral context, compounded by the “bad” activity and poverty data and the fact that the Central Bank has lately reduced its foreign currency purchases to strengthen its reserves.



Tras el fiasco del Doroteo Guamuch, selección de futbol de Guatemala jugará otro torneo oficial en cancha prestada
 Sergio Morales1 Mins read