‘Argentina has made huge progress in a very short time,’ says Citi exec
 Juan Marcos PollioUpdated 1 hour Ago4 Mins read
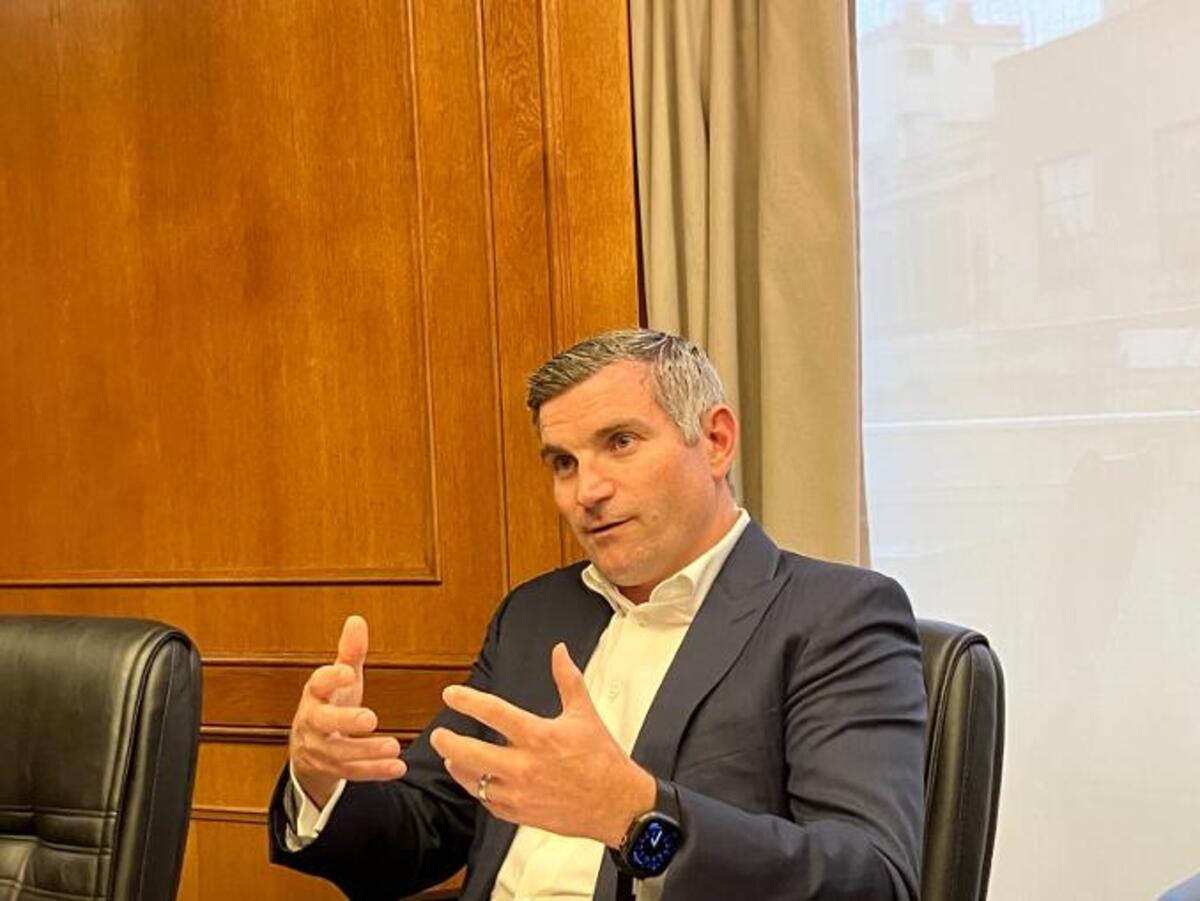

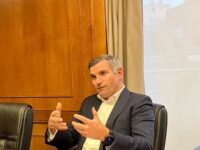
After eight years away from Argentina, Sam Hewson, Citibank’s Head of FX Sales, returned to the country amid heightened volatility in both international markets — driven by the AI boom, the U.S. elections, and the war in the Middle East and the domestic market, which is increasingly focused on next year’s elections.
At Citi’s offices in Buenos Aires, Hewson spoke with the Herald about developments in the global foreign exchange (FX) market, which has experienced exceptional volatility over the past 12 months.
“The FX volumes we’ve recorded this year are the best we have seen since 2010 in our global franchises,” he said.
He noted that rising geopolitical tensions and risks are creating greater volatility, forcing clients “to be more thoughtful around their hedging and their risk management.”
From a geopolitical perspective, he said the need for resiliency has never been greater, as clients “will no longer have a single geographic supply base for their production” following the “previous shocks that they’ve been through.”
This means that exposures have become “more complex” due to the diversification of supply chains, greater logistical challenges, and the need to operate across multiple currencies in a “dynamic, evolving space.”
As a result, he argued, this environment has increased the need for more active risk management, as well as greater hedging.
Carry trades: The dollar’s diminished appeal and growing interest in Latin America At another point during the interview, Hewson said his clients “don’t have great conviction on the dollar in general” when considering carry trades involving the U.S. currency.
He emphasized, however, they have more stronger conviction in emerging markets, particularly in Latin America.
“Latin America has been a strong conviction story from our clients who have been looking to invest in currencies that have strong signals from a carry perspective, from a momentum perspective, and, to some extent, resilience from the interest rate environment and the fiscal environment,” he explained.
In this regard, he said clients have been looking for currencies backed by positive terms of trade and fiscal surpluses.
He clarified that the dollar is not often the currency used to fund those trades. “It’ll be through another currency, which will be the funding vehicle for that expression,” as is the case with the Japanese yen.
“The yen has long been a currency against which investors have sold a low-yielding currency and bought a high-yielding one like the Colombian peso or the Brazilian real,” he explained.
Argentina’s outlook for 2027 On his return to Argentina after eight years, Hewson said he had an extremely positive impression of the direction and momentum of the economy, as well as the reforms driving the changes.
Comparing the current economic situation with that of 2023, he noted: “It feels from an international point of view like a material positive change in dynamic and one in which huge progress has been made in actually a very short amount of time.”
Among the achievements of Javier Milei’s administration, he highlighted the improvement in the trade balance, the fiscal surplus, slowing inflation and a more stable exchange rate.
“All of that makes it much more attractive from an international institutional community, and we see that with our clients. We see that much more so now in the conversations we’re having with our clients looking to express positive views on Argentina, and we see that through the activity that we trade with our clients,” he said.
Regarding next year’s elections, he commented that any election, whether in Argentina or anywhere, creates a degree of uncertainty and volatility, although he could not say which direction that volatility would take.
“I think the overwhelming story in Argentina is one of positivity now,” he emphasized.
Jorge Lonegro, Citi’s Head of Markets for Argentina and South Sub-Cluster, who also took part in the interview, told the Herald that while “probably uncertainty will come during the elections time,” it is “totally manageable.”
Asked whether the peso was excessively overvalued, he replied that “the price is the price,” and that it is a consequence of foreign exchange flows, including export and, import activity and financial inflows.
Finally, regarding the government’s financing plan for 2027, he acknowledged that “they have been open that they have the ability to raise funding.”
The dollar: Tariffs, AI, and the Fed Asked about the dollar’s weakness in international markets since Trump’s return to the White House, Hewson said the currency had gone through a “challenging period” that began with “Liberation Day” in April 2025 and triggered an “initial knee-jerk sell-off in the dollar.”
At the time, he explained, markets had been positioned for a stronger dollar because a narrative of “American exceptionalism” was gaining traction in the United States.
“The macro community and our clients were expressing that through this long-dollar type exposure and long-dollar expressions in foreign exchange,” he said.
However, the introduction of tariffs worldwide “flipped that on its head and people started selling the dollar.” From that point onward, the idea of dollar devaluation became a relevant market hypothesis.
He believes, however, that this pessimistic narrative has now dissipated and that American exceptionalism is “actually becoming more of a relevant story again, particularly with the event of the AI supercycle and all of the productivity-trade-related activity and growth.”
This phenomenon is particularly evident in the United States, “but also in certain areas like North Asia, Taiwan, Korea, where they have been the benefactors of that AI supercycle.”
Hewson also noted that the Federal Reserve’s September interest rate hike, under Kevin Warsh’s leadership, was positively received by the market.
This has helped bolster the institution’s credibility, following earlier concerns about the degree of independence the current chairman of the U.S. central bank would mantain from the Trump administration.
“I think that is also no longer driving that weak-dollar theme,” he added.
Separately, André Secron, Citi’s Head of Latin America Corporate FX Sales, told the Herald that the value of the dollar is closely correlated with interest rates in the U.S.
Thus, while the new administration under Warsh has sent signals of independence that the market has welcomed, it has also introduced volatility through other channels.
“Now we have a Fed who already communicated to the market that he doesn’t want to communicate or give guidance on what’s going to happen to interest rates,” he said.
He added that this “adds some uncertainty as well into what is going to happen with dollars correlated to whether there’s going to be hikes or no hikes.”


Plazo fijo: cuánto se gana al colocar $1.000.000 durante un mes
El plazo fijo sigue siendo una de las alternativas más usadas por...
 Herakles033 Mins read